
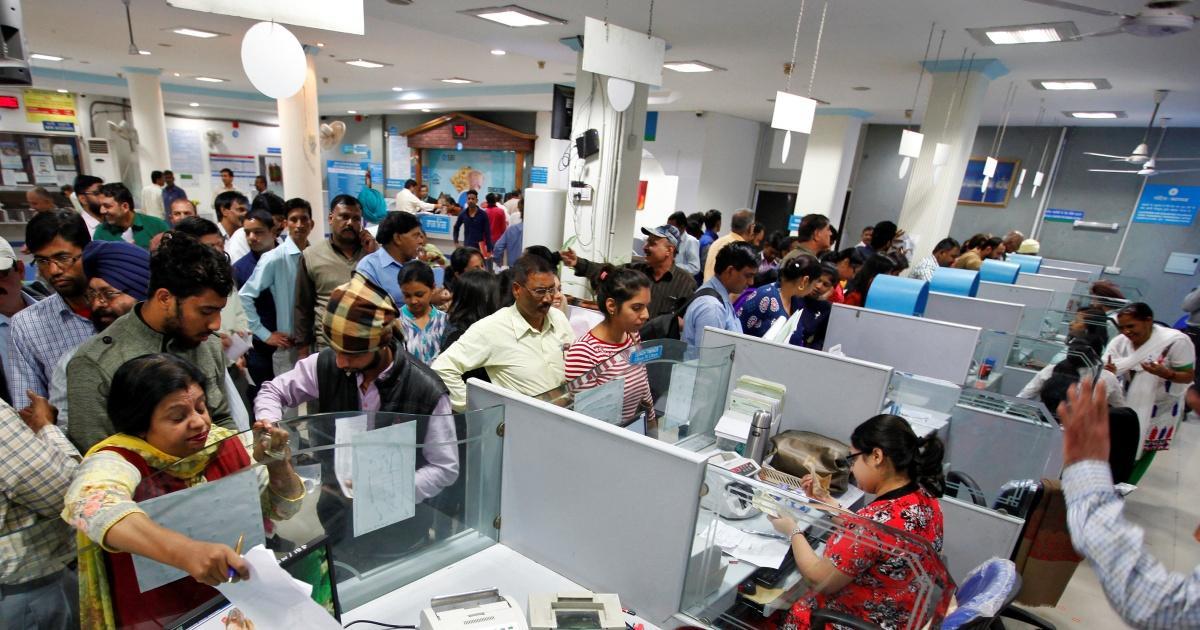
Every time a customer uses a bank account, there could be a charge waiting. Maintaining a minimum balance, withdrawing cash, using a card, missing a payment or even failing a transaction can come at a cost. India’s banks have turned everyday banking into a sprawling fee economy, where charges are often buried in tariff schedules, difficult to anticipate and harder to challenge.
The contradiction is striking. India has built one of the world’s most sophisticated digital payment ecosystems, making money transfers faster and cheaper than ever. Yet the cost of maintaining and using a bank account remains riddled with fees, penalties and surcharges. Despite repeated RBI interventions, questions persist over their transparency, proportionality and enforcement.
The imbalance is fundamental: banks know precisely what they charge, when and why. Customers often discover it only when they check their dwindling balances. A charge may be disclosed in the fine print, but that does not necessarily make it transparent to the consumer.
From accessing and moving money to withdrawing, depositing and maintaining an account, customers increasingly pay for the privilege of using their own money. Has banking become a service industry where the customer pays at every turn, often without fully knowing what the bill will be?
Transparency Gap
Banks disclose the billions they earn, not who pays the price
India’s banking fee economy is enormous. HDFC Bank reported ₹34,876 crore in fees and commissions in FY2026, against ₹31,899 crore in FY2025. ICICI Bank earned ₹25,742 crore in fee income in FY2026, while Axis Bank reported ₹24,444 crore. SBI reported ₹30,919 crore under commission, exchange and brokerage in FY2025, a differently classified category.
But these figures reveal little about what ordinary customers pay in minimum-balance penalties, cheque returns, failed mandates, ATM withdrawals and debit-card charges. Banks disclose aggregate fee income, not who pays what. Their revenues include retail, corporate and institutional charges, but there is no standardised public breakdown showing the contribution of individual retail charges.
How much do banks collect from minimum-balance penalties? Failed EMI mandates? ATM and debit-card fees? How many customers are charged, and how much is subsequently refunded? There is no comparable industry-wide disclosure. That is the transparency deficit. The issue is not whether banks should charge for services, but whether charges reflect actual costs and whether customers can see what they are paying.
RBI’s Working Group on Customer Service in Banks flagged non-transparent charges and inadequate cost-based pricing as far back as 2006. Nearly two decades later, a standardised public Customer Charges Statement remains overdue.
Minimum Balance Trap
A penalty that hurts those with the least
Minimum-balance penalties expose the imbalance between banks and customers. RBI requires banks to notify customers of a shortfall and allow at least a month to restore the balance. Charges must be proportionate to the shortfall, and savings accounts cannot turn negative solely because of these penalties.
Yet violations persist. In February 2025, RBI fined Nainital Bank ₹61.40 lakh, among other violations, for imposing flat-rate penalties instead of proportionate charges. A published tariff does not make every deduction compliant with RBI rules.
Banks also differ sharply in their policies. Canara Bank waived minimum-balance penalties across savings accounts from June 1, 2025. ICICI Bank, meanwhile, requires new savings accounts opened from August 2025 to maintain monthly average balances of ₹15,000 in metro and urban branches, ₹7,500 in semi-urban branches and ₹2,500 in rural branches. The same basic service comes with vastly different financial obligations. For customers with limited savings, even a few hundred rupees can hurt.
ATM Transaction
When ‘Free’ Stops Being Free
Since May 1, 2025, banks can charge up to ₹23 per ATM transaction beyond the prescribed monthly free limits, plus applicable taxes.
But failed transactions caused by technical problems, communication failures or cash shortages cannot be charged. If an account is debited without cash being dispensed, the bank must reverse the amount within T+5 days. Delays attract compensation of ₹100 a day.
The rules are clear. Their implementation is the question. Are wrongful debits reversed automatically, or must customers detect the error, complain and chase the bank for their money?
The Cash Penalty
Is physical banking becoming more expensive?
Digital banking has made UPI and online NEFT transfers from savings accounts generally free. Physical banking, however, comes with its own price. Punjab National Bank, for instance, allows three free cash-deposit transactions a month in savings accounts, after which it charges ₹50 per transaction, subject to prescribed conditions. Additional cash-handling charges may apply depending on the amount deposited.
The burden is uneven. Salaried customers who receive money digitally may rarely visit a branch. Small traders, pensioners and self-employed people who depend on cash may pay more frequently.
Is banking becoming cheaper for the digitally equipped and more expensive for those who still depend on cash?
Cascading Charges
How one financial setback triggers several deductions
The real burden may lie in the chain reaction of charges. A borrower misses an EMI because of insufficient funds. The mandate fails, a return charge follows, and the lender may impose a separate penalty. Another scheduled payment may then fail because the account remains short.
One liquidity crunch can trigger multiple deductions, with additional interest or consequences depending on the loan terms.
A single ₹500 charge is one thing. Several charges arising from the same financial setback are quite another. Banks should disclose when one failed payment can trigger multiple penalties.
The Loan Bill
When Charges Begin Before the EMI
For borrowers, the interest rate is only part of the cost. Processing, documentation, legal, valuation, insurance and mandate charges can add significantly to the bill. Prepayment and default may bring further costs.
RBI’s Key Facts Statement (KFS), mandatory for new retail and MSME term loans sanctioned from October 1, 2024, requires lenders to disclose the Annual Percentage Rate (APR), including interest and applicable charges. Third-party charges must also be separately disclosed.
Undisclosed fees generally cannot be imposed later without the borrower’s explicit consent.
The reform is important, but disclosure is not enough. Borrowers must receive the KFS in advance and be able to understand and compare the actual cost of competing loans. A technically complete document is useless if customers cannot decipher the final bill.
Uncomfortable Evidence
Consumers have been complaining for years
Banking-charge grievances long predate digital payments. In FY2016-17, RBI’s Banking Ombudsman data showed that 5.5 per cent of complaints concerned charges levied without prior notice, including minimum-balance penalties, processing fees, prepayment penalties and cheque-collection charges.
Complaint classifications have since changed, making direct comparisons difficult. But customer grievances remain substantial.
In FY2024-25, RBI’s Ombudsman offices received 2,96,321 complaints, up from 2,93,924 the previous year. These included 86,670 complaints relating to loans and advances, 49,913 concerning deposit accounts, 49,951 involving mobile and electronic banking, and 50,811 credit-card complaints.
These figures cover broader banking grievances, not just service charges. They nevertheless point to persistent friction between banks and customers. The bigger problem is reactive redressal. Customers must spot a deduction, establish that it may be improper, find the relevant rule, complain and, if necessary, escalate the matter.
For a deduction of ₹21, ₹50 or ₹100, many simply give up. The amount is too small to justify the effort. A system that depends on customers detecting violations allows repeated small deductions to escape scrutiny.
A Lame Duck RBI?
The Regulator Has Intervened. But Is It Enough?
RBI has capped ATM charges, mandated reversals and compensation for failed transactions, introduced the KFS regime and tightened rules on loan penalties. Since January 2024, penal charges on loans must be reasonable and proportionate to the breach of contractual terms. They cannot be capitalised, and lenders must disclose their amount and reason. RBI has specifically sought to prevent penal charges from becoming an additional revenue stream.
But regulation must be measured by compliance, not just circulars issued. Why must customers discover prohibited deductions before banks correct them? Why do questionable practices surface only after complaints accumulate? And why is there still no common public reporting system for major retail charges? The regulatory authority has clearly failed to ensure the best for the consumers.
India has built one of the world’s most sophisticated digital-payment ecosystems. It is time to bring the same transparency to the price of banking. Customers can see every deduction from their accounts. They deserve to know the economics behind those deductions too.
BOX
GST that turns a ₹500 charge into ₹590
There is another layer that consumers frequently overlook. Where GST applies, the tariff displayed by the bank is not necessarily the final amount debited. A ₹500 taxable charge can become ₹590 after 18 per cent GST.
The tax itself is not a hidden bank charge. But from a consumer perspective, the relevant number is the amount actually leaving the account.
A tariff schedule that displays ₹500 while the statement ultimately records ₹590 may be legally adequate if GST is appropriately disclosed. However, it is still less useful to a consumer than an upfront display of the final payable amount.
The principle should be simple: show the customer the final price, not merely the pre-tax component.
NON-TRANSPARENT FEE HAUL
| Bank | fee-related figure | Period | What it actually represents |
| HDFC Bank | ₹31,898.6 cr | FY25 | Fees & commissions |
| ICICI Bank | ₹25,742 cr | FY26 | Fee income |
| Axis Bank | ₹24,444 cr | FY26 | Fee income |
| SBI | ₹30,918.6 cr | FY25 | Commission, exchange & brokerage |
| PNB | ₹7,023 cr | FY25 | Fee-based income |
THE EVERYDAY FEE TRAP
ACCOUNT
Minimum-balance shortfall • account maintenance • statements • closure
CASH
Cash deposits beyond free limits • cash withdrawals • non-home branch transactions
ATM
Other-bank ATM after free quota • certain card services • international ATM usage
PAYMENTS
Cheque return • NACH/ECS return • failed/returned transactions
CARDS
Annual maintenance • replacement • international usage • certain premium-card services
LOANS
Processing • documentation • valuation • legal • insurance-related costs • penal charges • restructuring/prepayment where applicable
OTHER
Demand drafts • duplicate documents • special requests • forex/remittance services
THE CHARGE CASCADE
Insufficient balance
↓
EMI/NACH fails
↓
Return/bounce charge
↓
Balance remains inadequate
↓
Another scheduled payment fails
↓
Another charge
↓
Possible contractual interest/other consequences
The real consumer cost is the chain, not necessarily any single charge
RBI’S ‘NOT SO EFFECTIVE’ WARNINGS
2006: RBI Working Group records complaints of unreasonable and non-transparent charges
2015: RBI requires minimum-balance penalties to be proportionate and preceded by notice
2021: RBI strengthens ATM customer-charge framework
2023: RBI says penal charges must not become a revenue-enhancement tool
2024: KFS introduces standardised all-in-cost disclosure for eligible loans
2025: RBI penalises Nainital Bank ₹61.40 lakh for, among other issues, improper minimum-balance penalties
2025: RBI Ombudsman offices receive 2.96 lakh complaints