

Auditor seeks to withdraw Supreme Court affidavit alleging fabricated accounts; move comes three days after he accused a top ISKCON functionary of pressuring him to change his testimony
Aiyer V.L. Varadarajan, a Mysuru-based advocate and chartered accountant who served for years as auditor of ISKCON’s Bengaluru operations, has asked the Supreme Court to allow him to withdraw a counter-affidavit filed in January 2026 in Review Petition (Civil) No. 1896 of 2025. The affidavit contained allegations concerning the alleged fabrication of accounts and other records linked to the Bengaluru temple dispute.
The reversal is significant because the January affidavit contained serious allegations about the creation of backdated accounts, audit reports and other records relating to the society registered in Bengaluru in 1978. Varadarajan had attributed the alleged acts principally to instructions and pressure from the President of ISKCON, Bangalore, Madhu Pandit Dasa, while acknowledging his own role in preparing and signing certain records.
In his fresh affidavit dated October 6, 2026, Varadarajan retracts the January affidavit in full. He says he signed it without properly reviewing its contents and alleges that representatives of ISKCON Mumbai took advantage of a period of personal and financial vulnerability. He says the latest filing is intended to ‘correct the record’ and restore the position he claims to have maintained before July 2025.
A striking reversal within days
On October 3, 2026, Varadarajan filed a further signed complaint at Tilak Marg police station in New Delhi, continuing his complaint dated January 22, 2026. The copy supplied for this report bears the police station’s stamp and an endorsement recording Daily Diary (DD) No. 57 dated October 3.
In the complaint, Varadarajan alleged that Madhu Pandit Dasa had threatened and pressured him over the affidavit he filed before the Supreme Court in January and had sought to induce him to make a false statement.
According to Varadarajan, Madhu Pandit Dasa’s driver conveyed a message asking him to visit Dasa’s office and claim that ISKCON Mumbai had offered him Rs 5 crore to change sides. Varadarajan denied that such an offer had been made, stating that he had not been in contact with ISKCON Mumbai for about a year.
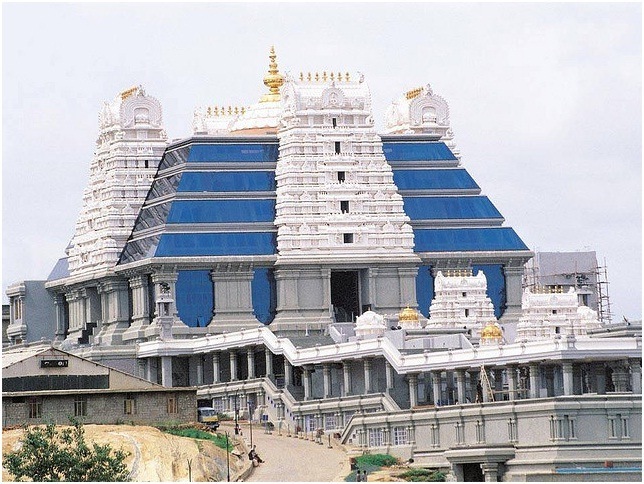
Varadarajan further alleged that, during a meeting at Hare Krishna Hill in Bengaluru, which he said was video-recorded, Madhu Pandit Dasa offered him Rs 1 crore over and above his unpaid professional fees.
According to the complaint, Dasa also said he had recorded their conversation and would file a criminal conspiracy complaint against two devotees from Mumbai. Varadarajan alleged that Dasa described the two men as murderers and warned that his life would be at risk. He said he interpreted the remarks as a veiled threat.
Varadarajan also alleged that, at a subsequent meeting in Mysuru, Dasa insisted that their mobile phones be kept away to prevent any recording. Dasa then allegedly offered him a sum exceeding Rs 50 crore as payment, with interest, for his past professional services. Varadarajan said he refused the offer and subsequently sent Dasa a list of the services he had provided and the years in which he had rendered them.
The October 3 complaint further alleged that Madhu Pandit Dasa had been collecting messages and documents to create the impression that Varadarajan’s January affidavit had been motivated by money. Varadarajan denied this.
He asked the police to register a first information report (FIR) against Dasa and anyone else found to be involved, provide immediate protection to him and his elderly mother, preserve relevant call records, CCTV footage, messages and video recordings, and record his statement. He said he was approaching the authorities to place what he regarded as the truth on record, rather than for personal gain.
Two days later, on October 5, representatives of ISKCON Mumbai said Varadarajan appeared at the Supreme Court accompanied by Madhu Pandit Dasa and another associate. On October 6, Varadarajan, through a new advocate-on-record, filed an affidavit seeking permission to withdraw his January counter-affidavit in full.
The October 6 affidavit does not refer to the October 3 police complaint or address the allegations of threats, inducements and monetary offers that Varadarajan had made against Dasa in that complaint.
What Varadarajan alleged in January
In his January 2026 filings, Varadarajan said he had been associated with the Bengaluru temple since the mid-1980s and had served as its auditor from around the 1989–90 financial year. He stated that the audited financial statements he prepared were regularly forwarded to ISKCON’s head office in Mumbai.
He further alleged that, around 2001, Madhu Pandit Dasa had asked him to fabricate and backdate audited financial statements covering approximately 12 years in the name of the society registered in Bengaluru in 1978.
According to Varadarajan’s January account, he subsequently realised that the accounts were being used to project continuity for a society that had remained inactive until 2001.
Varadarajan also alleged that he had personally witnessed the manipulation of records at the Registrar of Societies, including the removal, replacement and insertion of documents and the misuse of official seals. He further claimed knowledge of alterations to Bangalore Development Authority records.
He alleged that minutes of governing-body and general-body meetings that had never taken place were fabricated and backdated to create a false historical record of the society’s office-bearers.
In January, Varadarajan also told Delhi Police that he feared for his safety and that of his mother following these disclosures. On January 24, 2026, he approached the Supreme Court seeking protection from coercive action, conditional immunity and protection for himself and his family against alleged threats from Madhu Pandit Dasa. He also undertook to cooperate with any inquiry or verification.
What the October 6 affidavit now says
The fresh affidavit reverses the direction of the allegations of pressure. Varadarajan now says that, during a difficult period in his personal life, representatives of ISKCON Mumbai aggravated his grievances against Madhu Pandit Dasa and provided him with temporary financial assistance in the form of gold jewellery valued at approximately Rs 72 lakh.
He says he pledged part of the jewellery with a bank and subsequently came under pressure to return it.
According to the affidavit, he was told that filing an affidavit would bring the litigation to an end and protect him from further harassment. He alleges that he was also warned that refusing to cooperate could result in his being made an accused and arrested.
Varadarajan now says that he signed the January counter-affidavit and police complaints prepared by ISKCON Mumbai and its lawyers without reviewing their contents.
He further alleges that, after receiving notice in the Kolkata criminal case, he was pressed to make additional statements. When the investigating officer travelled to the Pune–Lonavala area to record his statement on video, representatives of ISKCON Mumbai allegedly directed what he said, leaving him feeling unable to give his own account.
He also says he declined to make a statement before a magistrate under Section 183 of the Bharatiya Nagarik Suraksha Sanhita (BNSS) because he feared the legal consequences.
The October 6 affidavit states that Varadarajan received no financial incentive for making the fresh filing. He has offered to deposit the gold jewellery said to have been provided to him with the Supreme Court, subject to directions concerning the portion pledged with the bank.
What the new affidavit does, and does not, establish
The new affidavit retracts the allegations and what Varadarajan calls the ‘purported confessions’ contained in his January filing. However, the retraction does not, by itself, resolve the documentary questions at the centre of the long-running litigation.
In particular, the fresh affidavit does not directly explain the existence of historical audit reports, the alleged two sets of accounts for 1990–91, or subsequent accounts said to have been signed by Varadarajan in the name of VLV & Co.
It also does not directly address the filing, on August 9, 2001, of 12 years of annual returns certified by him, along with office-bearer records, at the Registrar of Societies. According to the draft material, these documents were filed in a single exercise by Madhu Pandit Dasa.
Varadarajan instead says that the allegations in his January affidavit were not independently verified by him. He has asked the Supreme Court to assess both his earlier and his present accounts against the contemporaneous documentary record.
The fresh affidavit does not refer to the October 3 police complaint. The copy supplied for this report bears Varadarajan’s signature and the Tilak Marg police station stamp, along with DD No. 57 dated October 3, 2026.
The proximity between the police complaint and the subsequent retraction is likely to invite scrutiny when the competing versions are assessed. However, the filing of a police complaint does not establish the truth of the allegations it contains.
Larger Bengaluru Temple Dispute
The underlying litigation dates back to the early 2000s and concerns competing claims over the Bengaluru temple and associated assets.
ISKCON’s Mumbai-based society, registered in 1971, maintains that the temples established under its founder, Srila Prabhupada, belong to the Mumbai society and operate as its branches.
According to the Mumbai society, Srila Prabhupada opened eight temples across India during his lifetime, which ended in 1977, and all eight were owned by and functioned as branches of the 1971 society. It maintains that he did not register any other ISKCON society in India. The Mumbai society says it now has more than 400 branches across the country.
The Mumbai society further alleges that the separate society registered in Bengaluru in 1978 became dormant and was subsequently revived through fabricated or backdated records by Madhu Pandit Dasa, members of his family, chartered accountant V.L. Varadarajan and other associates.
Madhu Pandit Dasa and the Bengaluru side dispute this account. They maintain that the 1978 Bengaluru society is the relevant legal entity for the temple and its property.
The Mumbai society, by contrast, alleges that Dasa and members of his family or close circle used the 1978 society to take control of assets that, according to Mumbai, belonged to the 1971 society.
Karnataka High Court and the Supreme Court
In 2011, a Division Bench of the Karnataka High Court made adverse findings concerning the production of accounts and other records in the name of the 1978 Bengaluru society.
The judgment referred, among other matters, to 12 years of audited accounts and office-bearer records that, according to the High Court, had been filed only around 2001–02. It described certain records as having been created to give life to a defunct society.
The high court further held that Madhu Pandit Dasa, with the assistance of members of his family and chartered accountant V.L. Varadarajan, had attempted to take over the temple through the fabrication of documents, accounts and resolution books.
In May 2025, however, the Supreme Court set aside the High Court judgment and ruled in favour of the 1978 Bengaluru society in the civil dispute. The Supreme Court took a different view of the material and held that the High Court’s discussion of alleged fabrication and manipulation was not relevant to the issue before it.
ISKCON Mumbai has since sought a review of the Supreme Court judgment, arguing, among other things, that allegations of fraud, fabrication and contradictory historical admissions could not be treated as irrelevant. The review proceedings remain pending, according to the material supplied for this report.
Madhu Pandit Dasa’s earlier statements
The Mumbai society relies heavily on statements and pleadings filed by Madhu Pandit Dasa in various legal proceedings before the dispute emerged in its present form.
It says that, in a 1986 deposition, Dasa described himself as president of the Bengaluru temple and stated that it functioned under the direct control of the Bombay office.
The Mumbai society also cites a 1994 consumer proceeding in which Dasa allegedly described ISKCON Bengaluru as a branch. It further relies on three civil suits filed between 1999 and early 2001 in which, according to the society, Dasa described himself as president of the Bengaluru branch of the 1971 Mumbai society, referred to the Mumbai society as the owner of the temple property, and stated that the Bengaluru accounts were sent to Mumbai annually for consolidation.
The Mumbai society argues that these earlier pleadings are difficult to reconcile with the subsequent claim that the 1978 Bengaluru society had continuously owned and operated the temple since its inception.
The Bengaluru side disputes the conclusions that Mumbai seeks to draw from these documents.
Accounts, tax records and the auditor’s role
The accounting history is central to the dispute. ISKCON Mumbai relies on income-tax records indicating that the Bengaluru branch’s accounts were included in the 1971 Mumbai society’s returns until around 2000, while returns in the name of the separately registered Bengaluru society were filed only thereafter.
To support its contention that the 1978 Bengaluru society remained inactive until 2001, the Mumbai society cites a passage from assessment orders issued in 2006 by the Assistant Director of Income Tax (Exemption), Mumbai.
The passage, as reproduced in the supplied material, states that the registered Bengaluru society had adopted the Mumbai society’s Bengaluru branch accounts and filed them with its income-tax returns from the 2000–01 assessment year onwards, without the Mumbai society’s consent or the assessing officer’s prior approval. It also states that the Bengaluru society had not filed income-tax returns in Mumbai or Bengaluru before the 2000–01 assessment year.
The draft also refers to disciplinary proceedings before the Institute of Chartered Accountants of India (ICAI) concerning Varadarajan’s audit work. A disciplinary committee reportedly found professional misconduct relating to certain accounts, including two sets of accounts for 1990–91 and accounts signed in the name of VLV & Co. after the firm was said to have closed.
The ICAI Council subsequently exonerated him in an ex parte proceeding, and the Karnataka High Court declined to interfere with that outcome.
Varadarajan’s January 2026 affidavit appeared to offer an insider’s account of how the disputed records had allegedly been created. His October retraction has now introduced a fresh question: why did he make the January statements, seek protection against alleged threats, file another police complaint against Madhu Pandit Dasa on October 3, and then seek to withdraw his earlier affidavit on October 6?
The sequence does not, by itself, establish which version is accurate. It does, however, underscore the importance of examining the documentary evidence independently of the auditor’s changing account.
Separate development on Akshaya Patra
Separately, the supplied material refers to an order issued by the West Bengal School Education Department on September 11, 2026, withdrawing an approval granted to the Akshaya Patra Foundation on August 21, 2026, to provide midday meals under the PM POSHAN scheme in specified areas.
The order is said to record the competent authority’s decision without setting out reasons for the withdrawal.
Madhu Pandit Dasa is chairman of the Akshaya Patra Foundation. The Mumbai society has also alleged that Dasa and his brother-in-law took control of the Akshaya Patra programme, as well as the Bengaluru temple, which it claims rightfully belongs to the 1971 society.
These claims require separate verification. The Akshaya Patra development should be retained in this report only if a clear and independently established connection to the central temple dispute can be demonstrated. Otherwise, it would be better treated as a separate story.
Questions before the SC
The Supreme Court is considering a review in which allegations concerning the fabrication of documents and accounts form part of the wider dispute. Varadarajan’s successive affidavits and police complaints have added another layer of controversy.
The immediate issue is not simply which of the auditor’s two versions should be believed. The Court may need to assess the independent documentary record, including audit reports, statutory filings, earlier court pleadings and tax records, alongside the circumstances in which the January affidavit was made and subsequently retracted.
The competing allegations of pressure and inducement will also need to be assessed through appropriate legal proceedings and evidence.
For now, the auditor’s reversal has complicated an already protracted dispute. It has not, by itself, settled the questions of ownership, the authenticity of the disputed records or the responsibility of any individual for their alleged creation.
Publication note: The allegations summarised in this report are contested, and the review proceedings remain pending according to the supplied material. The police complaints and affidavits do not, by themselves, establish the truth of the allegations made in them. The October 6 filing is a request to withdraw the January affidavit; it is not a judicial determination of the competing accounts.